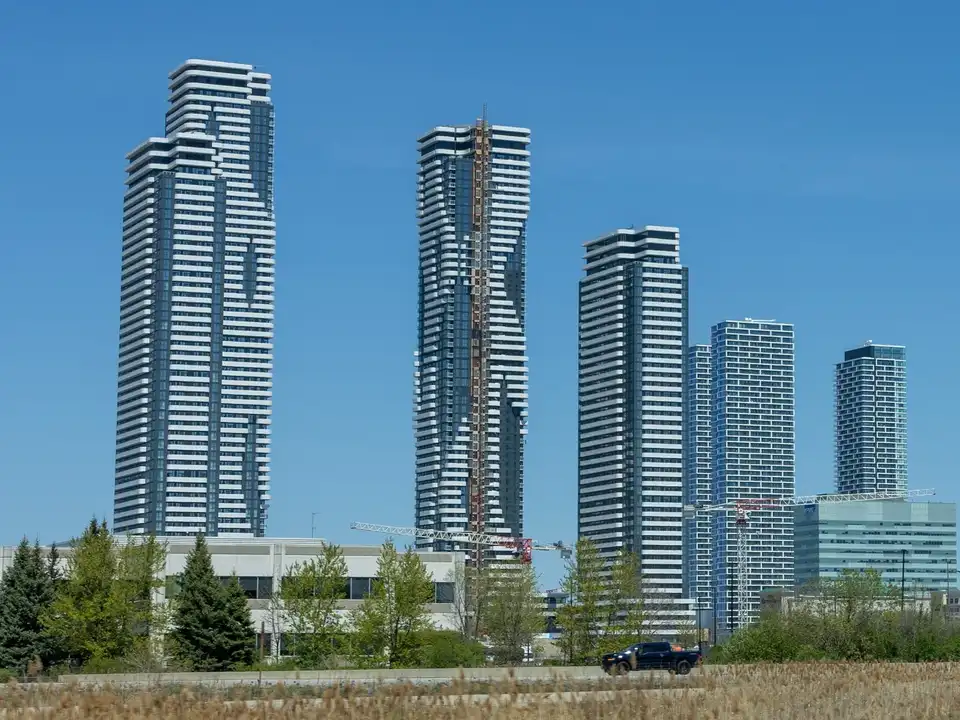
ReverseMortgageVaughan.ca explains how a reverse mortgage on your Vaughan condo works if you are 55 or older. A standard condo unit registered in your name can qualify, whether it’s in a Vaughan Metropolitan Centre tower or an older building in Thornhill. You keep living there, and no monthly mortgage payment is required on the condo.
Condo fees, Vaughan property taxes and home insurance remain your bills. Borrowed money isn’t income, so the mortgage money isn’t taxed. Your Old Age Security and Guaranteed Income Supplement stay the same too.
Vaughan’s condo buildings
Condos are now a big part of Vaughan’s housing. Apartments in buildings of five or more storeys made up 13.2% of the city’s occupied homes in the 2021 Census (Statistics Canada, Census Profile 2021).
The Vaughan Metropolitan Centre (VMC) has most of the city’s tallest buildings. Its towers went up around Highway 7 and Jane Street after the TTC Line 1 subway reached VMC station on December 17, 2017. Concord, Woodbridge and the Vaughan side of Thornhill have their own mid-rise and high-rise buildings, many of them older.
What Vaughan condos are selling for
The benchmark price for a Vaughan condo apartment was $523,100 in September 2026, down 4.92% from a year earlier (TRREB Market Watch, September 2026). The median condo apartment sale that month was $510,000, across 62 sales. The condo townhouse benchmark was $747,300.
Prices vary by area. These are median selling prices for condo apartments from April to June 2026 (TRREB Community Market Report, Vaughan, Q2 2026).
| TRREB community | Median condo apartment price | Sales |
|---|---|---|
| Vaughan Corporate Centre (VMC area) | $490,000 | 41 |
| Beverley Glen | $500,000 | 29 |
| Concord | $520,000 | 41 |
| Crestwood-Springfarm-Yorkhill | $632,000 | 34 |
| Brownridge | $710,000 | 22 |
How much you could get on a Vaughan condo
The most you could qualify for depends mainly on the age of the youngest owner and the condo’s appraised value. Here’s the most you could qualify for on a condo worth $523,100, Vaughan’s September 2026 condo apartment benchmark.
| Age of youngest owner | Up to this much of the value | On a $523,100 condo |
|---|---|---|
| 55 | 46.05% | Up to about $241,000 |
| 60 | 48.55% | Up to about $254,000 |
| 65 | 50.55% | Up to about $264,000 |
| 70 | 52.85% | Up to about $276,000 |
| 75 | 57.75% | Up to about $302,000 |
| 78 and older | 60% | Up to about $314,000 |
These are ceilings, not quotes. Lenders look at a condo a little differently than a house, and the appraisal sets the final figure. Taking less than the full amount is fine, and interest builds only on what you actually take out.
An illustrative example
Picture a widow aged 75 who owns a one-bedroom condo near VMC station. Condo apartments in the Vaughan Corporate Centre area sold at a median of $490,000 from April to June 2026. At 75, she could qualify for up to 57.75% of $490,000, which is up to about $283,000.
She still owes $60,000 on her current mortgage. That $60,000 is paid off first from the new mortgage money, which leaves up to about $223,000 for her to use. She has no required monthly mortgage payments, and she keeps paying her condo fees, property taxes and insurance.
What lenders check in a condo building
A lender looks at three things with a condo: your unit, your building and its location. The building review is what makes a condo different from a house.
The condo corporation’s finances and repair
Lenders review the condo corporation that manages your building. They look for sound finances, reasonable condo fees and a building in good repair. The corporation’s rules must also allow the mortgage.
The four lenders don’t judge every building the same way. HomeEquity Bank (CHIP), Equitable Bank, Home Trust and Bloom can each give a different answer on the same Vaughan condo. Knowing which lender suits which building is part of a broker’s job.
Newer towers
Many VMC towers are recent, and a newer unit can still qualify. Because each lender reviews the building on its own terms, a new tower can get different answers from different lenders.
Leasehold condos and co-ops
Leasehold condos, where you don’t own the land, usually don’t qualify. Co-ops, where you own shares instead of the unit itself, usually don’t qualify either. If your building is one of these, ask first, before you pay for anything.
Condo townhouses
A condo townhouse is reviewed along with its condo corporation, the same as an apartment. A freehold townhouse with no condo corporation is treated like a house.
Keeping the condo or selling it
Some owners think about selling and buying something smaller. Moving has real costs. If you bought another condo at Vaughan’s $510,000 median, Ontario land transfer tax alone would be $6,675 (Ontario, calculating land transfer tax). Vaughan has no city land transfer tax on top of it.
Agent fees, legal fees and movers come on top of that tax. The cost of downsizing in Vaughan is worth knowing before you list.
What stays yours
You stay the owner. The lender never owns your condo, and you can stay as long as it’s your main home and you keep up the taxes, insurance and upkeep.
Even if condo prices in Vaughan fall, your debt can never pass the unit’s fair market value when the mortgage comes due, so long as the taxes, insurance and upkeep are looked after. All four lenders include it, and it is typically called the no negative equity guarantee.
Because nothing is paid each month, interest keeps adding to the balance. Over the years, rising Vaughan condo values often make up for some or all of that interest, so your equity isn’t certain to shrink. You can test your own numbers in the Vaughan reverse mortgage calculator.
How Richard helps Vaughan condo owners
For a Vaughan condo, Richard Hopkins, Mortgage Broker, compares every reverse mortgage lender in Canada. His email then sets out every lender compared, and the best deal for your home and goals. Should a HELOC or another route fit your condo better, expect a recommendation based on your situation, even if it’s not a reverse mortgage.
Condo owners hear from Richard by email first, then phone or video call. A son or daughter can be copied on each email. You never need to visit an office. Two visits happen in person: the appraiser comes to your unit, and you meet your own lawyer for independent legal advice.
You pay Richard nothing. His brokerage is paid by the lender once the mortgage funds. The appraisal and your lawyer’s fee are still costs, and the guide to reverse mortgage costs in Vaughan explains each one.
What Richard does for you
- Every reverse mortgage lender in Canada compared for your condo
- A check of which lenders suit your building, including newer VMC towers
- An estimate by age, based on what units like yours sell for
- The best deal for your home and goals, sent to you by email
- Help gathering your condo fee statement, tax bill and ID
- Help setting up the appraisal of your unit
- Help finding a nearby lawyer for your independent legal advice appointment (ILA)
- Updates your family can be copied on, at no cost to you
The choices next to each other
| What is compared | Sell and buy smaller | HELOC (home equity line of credit) | Reverse mortgage |
|---|---|---|---|
| You keep your condo | No | Yes | Yes |
| Monthly payments | None, since there's no loan | Required, and they rise with prime | No required monthly mortgage payments |
| Income test | None | Yes, a bank stress test | No income test like a bank's |
| Main costs | Agent fees, land transfer tax, legal and moving | Interest paid each month | Interest added to what you owe |
| Condo fees, taxes and insurance | Paid on the next home | Still yours | Still yours |
Related Vaughan guides
- How Much Does a Reverse Mortgage Cost in Vaughan?
- What Does Downsizing in Vaughan Really Cost?
- How Much Is Vaughan Property Tax for Seniors in 2026?
Sources
Every number here was checked on October 16, 2026.