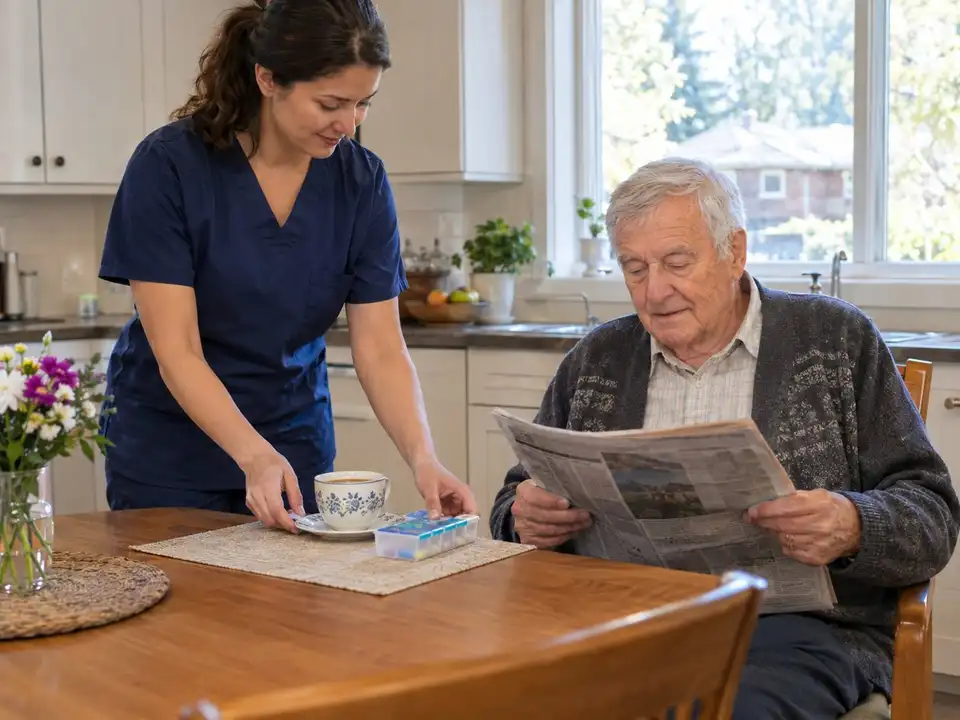
ReverseMortgageVaughan.ca shows you how to pay for home care in Vaughan from the value of the home you already own, if you are 55 or older. Help at home can mean a personal support worker, meals, cleaning or someone there overnight. Public home care covers some of it, and private help often covers the rest.
Vaughan had 52,690 residents aged 65 and older in the 2021 Census, 16.3% of the city (Statistics Canada, Census Profile 2021). Many of them want to stay in the homes they’ve owned for decades.
Public home care in Vaughan comes first
Ontario Health atHome arranges publicly funded home care in Vaughan. It’s also where you apply for long-term care later, so it’s the place to start.
Most of Vaughan is served by its Central area (Ontario Health atHome, Central). Two long-term care homes in south Woodbridge list Central West as their area instead (Ontario.ca, AgeCare Pine Grove). The office that serves you can vary by address, so give your full address when you call.
Publicly funded hours are limited. Many families add private help for the hours public care doesn’t cover. That private help is the part a family pays for.
Local help that costs little or nothing
Some help in Vaughan costs little or nothing. It’s worth using before you pay for private care.
Rides to appointments
YRT runs On-Request 65+, a door-to-door ride service for anyone aged 65 or older. It covers trips within 5 km of home on weekdays from 7 a.m. to 3 p.m. You book the same day by app, online or by phone, and the senior fare is $2.60 with PRESTO (YRT On-Request 65+).
Snow at the end of the driveway
The City of Vaughan clears the windrow for every home in the city. The windrow is the bank of snow the plow leaves at the end of your driveway. There’s no sign-up and no fee, but the City doesn’t clear the rest of the driveway (City of Vaughan, windrow clearing).
For the rest of the driveway, the City lists two groups for older residents (City of Vaughan, winter maintenance). Bridges of Love is a volunteer charity offering free snow removal to eligible residents 65 and older. CHATS runs a paid snow clearing program for people 55 and older, with subsidies for those who qualify. Check each group’s own website for this winter’s details.
How a reverse mortgage can pay for private care
A reverse mortgage lets you borrow against your Vaughan home without selling it. There are no required monthly mortgage payments, so the money can go to care instead of a loan payment.
A lump sum, monthly deposits or both
You can take the money as a lump sum, as monthly deposits, or as a mix of the two. Monthly deposits can line up with a regular care bill. Interest is charged only on the money you’ve actually taken.
What the money does and doesn’t affect
The mortgage money is borrowed, not earned, so it isn’t taxed. Old Age Security and the Guaranteed Income Supplement aren’t reduced by it either. Money left sitting in a savings account is another matter: the interest it earns there does count as income. That is one reason to take only what you need.
What you still pay
Property taxes, home insurance and upkeep are still yours. Vaughan has property tax help for some seniors, and the Vaughan property tax guide for seniors explains who qualifies.
An illustrative example
Picture a widow aged 78 who owns a home in Maple. Homes in Maple sold at a median of $1,135,000 from April to June 2026, across 102 sales (TRREB Community Market Report, Vaughan, Q2 2026). She has no mortgage left on her home.
At 78, she could qualify for up to 60% of $1,135,000, which is up to about $681,000. She doesn’t need that much. She takes a smaller amount as monthly deposits to pay for private help on the days her public home care doesn’t cover.
Her son and daughter are copied on every email. She stays the owner of her home. Her debt can never grow past the Maple home’s fair market value when the mortgage comes due, if she keeps the taxes, insurance and upkeep current. That rule is typically called the no negative equity guarantee.
If long-term care comes later
Long-term care can follow home care. The mortgage comes due once the last borrower has moved into long-term care for good. From then, a family commonly has up to a year to repay the lender or sell the house.
Nothing comes due while one spouse is in care and the other, also on the mortgage, still lives at home. Ontario sets one long-term care charge for every home. A basic room is up to $2,129.17 a month from July 1, 2026 (Ontario.ca, paying for long-term care). Local homes and their waiting lists are in the long-term care in Vaughan guide.
What it means for your family’s inheritance
Because nothing is paid each month, interest builds on the balance. Rising Vaughan home values often cancel out some or all of that interest. The equity left for your family won’t necessarily shrink. Whatever the home sells for above what’s owed goes to your family.
Some families also use part of the money to make the home safer, such as a walk-in shower or a main-floor bedroom. Paying for renovations that help you stay home explains how that works in Vaughan.
How Richard helps
When care is the goal, Richard Hopkins, Mortgage Broker, compares every reverse mortgage lender in Canada for your Vaughan home. His email shows every lender compared, and the best deal for your home and goals. Richard also weighs other ways to pay for care, such as a HELOC (home equity line of credit). Care plans then rest on a recommendation based on your situation, even if it’s not a reverse mortgage.
Care decisions involve the whole family, so a son or daughter can be copied on each email. Richard helps by email, phone or video call, and you never need to visit an office. You pay nothing for his help: the brokerage is paid by the lender after funding. Appraisal and legal costs still apply, and the guide to reverse mortgage costs in Vaughan lists them.
What Richard does for you
- An estimate of how much your home could put toward care, by age
- Your Vaughan home checked with every reverse mortgage lender in Canada
- The best deal for your home and goals, emailed to you
- Advice on a lump sum, monthly deposits or a mix of both
- A look at other ways to pay, such as a HELOC (home equity line of credit)
- Your children copied on every email, if you'd like
- Help finding a nearby lawyer for your independent legal advice appointment (ILA)
- All of it free to you, since the lender pays the brokerage
Related Vaughan guides
- Where Is Long Term Care in Vaughan, and What Does It Cost?
- How Much Is Vaughan Property Tax for Seniors in 2026?
- How Much Does a Reverse Mortgage Cost in Vaughan?
Sources
Every number here was checked on October 16, 2026.
- Ontario Health atHome, Central
- Ontario.ca, AgeCare Pine Grove long-term care home (Central West contact area)
- YRT, On-Request 65+ service
- City of Vaughan, windrow clearing
- City of Vaughan, winter maintenance
- TRREB Community Housing Market Report, Vaughan, Q2 2026
- Ontario, paying for long-term care
- Statistics Canada, Census Profile 2021, Vaughan